Start with your household’s time horizon and funding
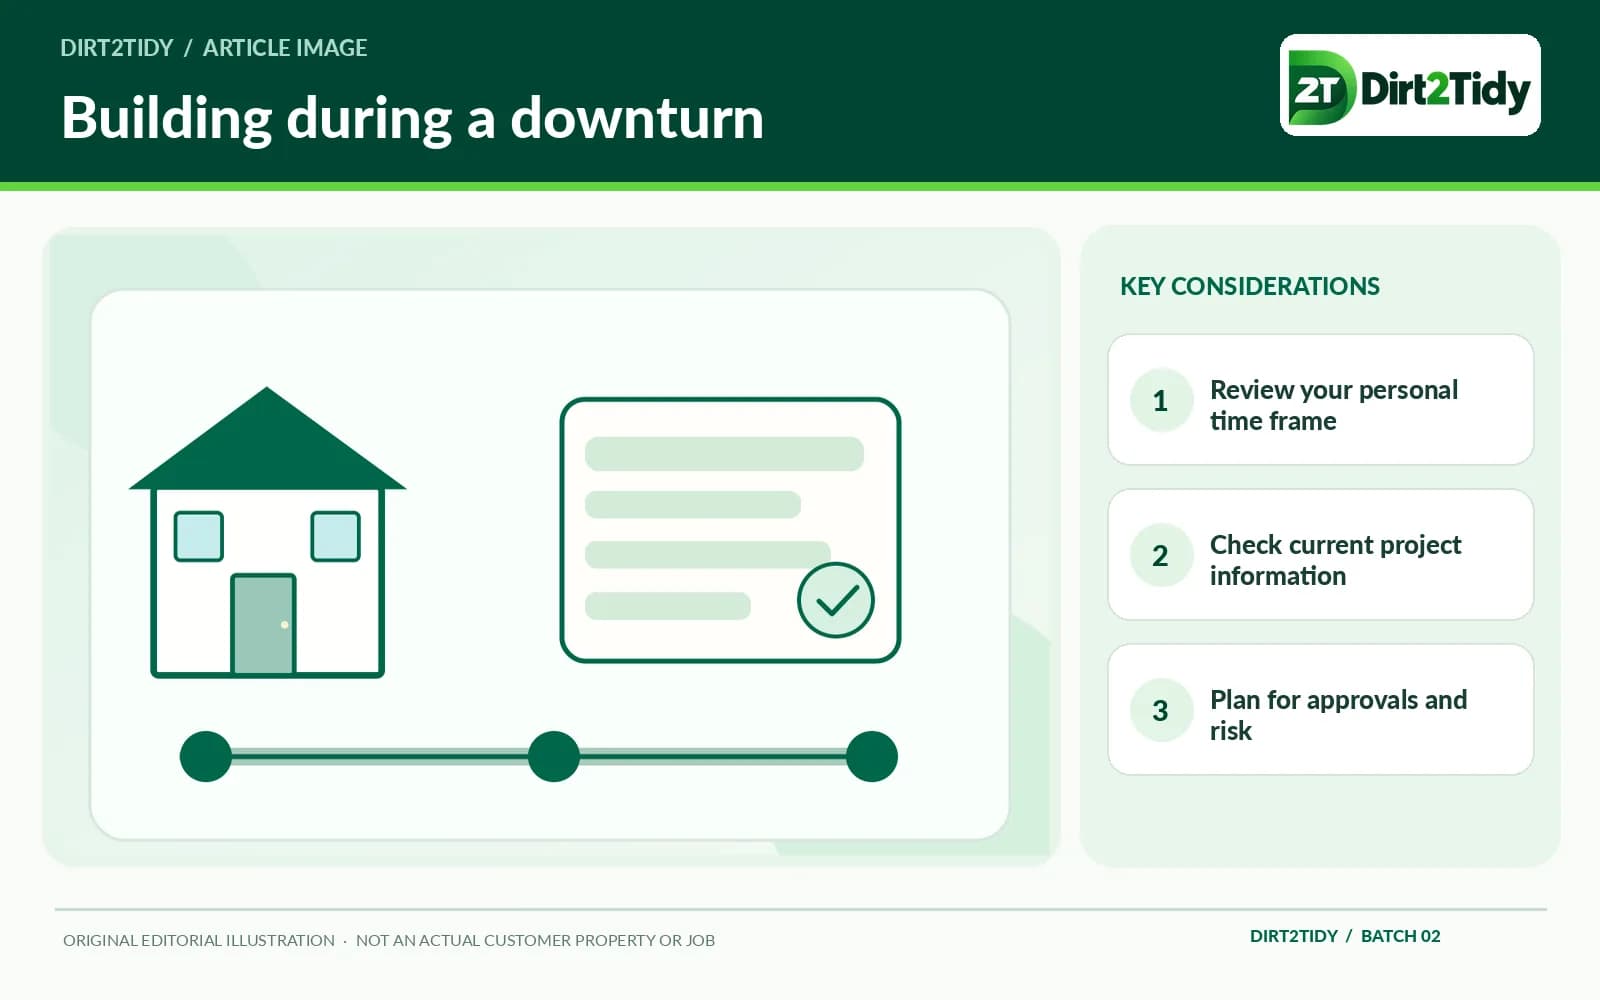
Write down where you intend to live, when you need the home and how certain those plans are. Ask your lender or qualified financial adviser to assess your own borrowing capacity, repayments and contingencies using current information. Do not rely on a national headline or calculator as personal finance advice.
Obtain current, comparable project information
Get dated quotes for land, design, site preparation, construction, services, approvals, insurance, temporary accommodation and likely variations. Ask a qualified builder to explain inclusions, exclusions, schedule, price changes and contract protections. Do not rely on old build-cost figures or a generic claim about recession discounts.
Check land, approvals and contract risks
Confirm title, planning, service access, site conditions, approval pathway and contract terms with the appropriate professionals and authorities. Ask what happens if costs, materials, construction times or finance change. Seek independent legal advice before signing a major contract.
Compare alternatives without predicting markets
Consider delaying, buying an existing home, changing the design or choosing another location using the same current assumptions. Record the date and source for each quote and note uncertainties. This article does not say that property values, interest rates or construction prices will rise or fall.
Decide with qualified advice and a contingency
Discuss the plan with an independent financial adviser, lender, builder and lawyer as appropriate. Set a contingency based on your own documented budget and advice rather than an online percentage. Revisit the decision if circumstances or quotes change.